Same Street, Different Math
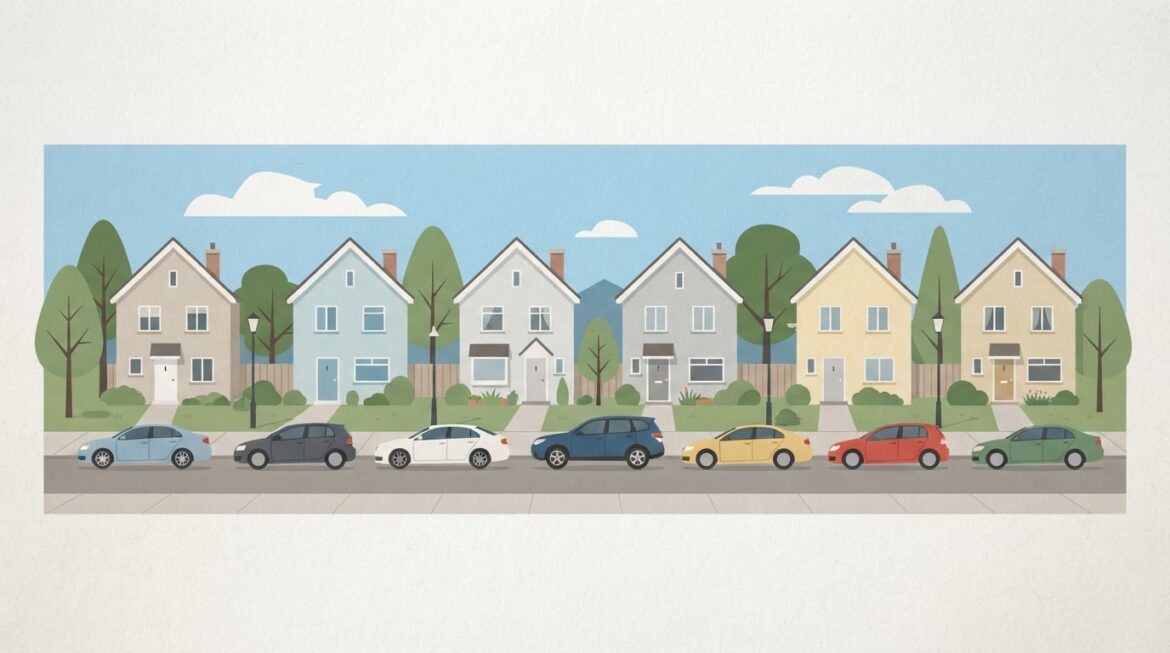
Two households on the same block, driving similar cars, can open their renewal notices and see numbers that don’t come close to matching. That gap feels personal, like one of them is being punished or the other is getting a favor. Neither is true. A premium is not a judgment of character; it’s a sum of separate variables, each weighted and multiplied by an insurer’s pricing model, and the variables rarely line up the same way for any two people, even next-door neighbors.
The confusion usually comes from assuming that “same street” means “same risk.” It doesn’t. Garaging address is only one input among many, and it’s often not even the biggest one. Age, credit-based insurance score where allowed, years licensed, claims history, the specific trim of the vehicle, the coverage limits chosen, and the deductible selected all sit on the same ledger. Change any one line item and the total shifts. Insurers aren’t comparing you to your neighbor at all — they’re running your data through their own model and running your neighbor’s data through the same model separately. The outputs just happen to land next to each other in your mailboxes.
Understanding which of these inputs you can influence, and which you’re stuck with, is the difference between shopping a policy intelligently and shopping it out of frustration.
Garaging Address Versus Driving Record
Garaging address — where the car is principally kept and driven — is a proxy for a cluster of risks: local accident frequency, theft rates, vandalism, weather exposure, litigation patterns, and even the density of uninsured drivers in the area. Two houses fifty feet apart can sit in different rating territories if a zip code, county line, or insurer-defined micro-zone splits between them. That’s not an error; it’s how the underlying loss data was sliced when the model was built. You cannot argue your way out of a rating territory, and you generally can’t change it without moving.
Driving record is the opposite kind of factor: it’s yours, it’s earned, and it moves over time. A single at-fault accident or a moving violation can raise a premium for several years, then fade as it ages off the lookback window insurers use — commonly measured in years, with the exact window varying by carrier and by state. A clean multi-year record is one of the few things that reliably pulls a rate down without you having to change anything about the car or the coverage.
The two factors also interact in a way that’s easy to miss: a bad record in a low-risk territory can still price out cheaper than a spotless record in a high-risk territory. Location sets the baseline; behavior moves you up or down from it. That’s why a driver who “did everything right” can still pay more than a neighbor with a minor ticket — the neighbor’s baseline was simply lower to begin with.
What you can actually influence here
- Driving record — through time and, in many states, through a completed defensive driving or accident-forgiveness program where offered
- Mileage-based risk — some insurers reward lower annual mileage or telematics-tracked driving behavior with a distinct discount
- Where the car is principally garaged, if you have a genuine choice — for example, a household with two addresses
What you can’t
- The rating territory itself and its underlying loss statistics
- Local weather and catastrophe exposure
- Regional litigation and repair-cost trends baked into that territory’s pricing
Vehicle, Coverage, and History Stack Up Separately
Once location and record are factored in, three more categories layer on top, and each is priced almost independently of the others.
The vehicle itself carries its own risk profile based on its price to repair, its safety rating, its theft rate, and its horsepower-to-weight ratio, among other things. A four-cylinder commuter sedan and a high-trim performance version of the same nameplate can carry noticeably different premiums for comprehensive and collision coverage even though liability exposure is similar, because the insurer is pricing the cost of fixing or replacing that specific vehicle, not just the risk that it causes a crash.
Coverage design — the limits you carry and the deductible you choose — is arithmetic you control directly. Every state requires some floor of liability coverage (the specific dollar figures vary by state and change periodically, so check your state insurance department’s current requirement rather than relying on a number you saw somewhere), but almost every driver who owns more than a used car with no loan on it should be evaluating whether that floor is actually adequate protection, separate from what the premium costs. Raising a deductible from a low figure to a higher one lowers the premium because you’re absorbing more of small-claim risk yourself; adding umbrella or higher liability limits raises it because the insurer is now on the hook for more in a serious claim. Neither move is “right” — they’re trade-offs between monthly cost and exposure in a bad-case scenario, and the correct answer depends on how much cash cushion you actually have, not on what a chart says you should carry.
History beyond the driving record covers things like continuous prior coverage (a gap in insurance history is itself a rating factor in most states), claims frequency on any vehicle in the household, and, in states that permit it, a credit-based insurance score. This category is the least intuitive because it has nothing to do with how you drive and everything to do with statistical correlation between financial behavior patterns and claims frequency across large populations. It’s also the category most likely to differ sharply between two neighbors who otherwise look alike on paper.
Put these three together and you can see why a side-by-side comparison of two “similar” drivers falls apart fast: the vehicle multiplier, the coverage arithmetic, and the history score are each doing their own independent math before the totals ever get added together.
A Factor-by-Factor Comparison Table
The table below groups the major rating inputs by how much control a driver actually has over them, and roughly how fast a change in that factor shows up in a premium.
| Factor | Driver’s control | Speed of effect on premium | Notes |
|---|---|---|---|
| Garaging address / rating territory | Very low | Immediate if you move | Set by insurer loss data for that zone, not by anything about you personally |
| Age and years licensed | None | Gradual, automatic | Premiums typically ease as a driver ages past the highest-risk bracket, independent of behavior |
| Driving record (accidents, violations) | High, over time | Slow — effects usually fade over a multi-year lookback window | The clearest lever a driver has, but it only moves with a clean stretch of years, not a single good month |
| Annual mileage / telematics behavior | Moderate to high | Fast — often reflected at next renewal | Requires opting into a mileage or usage-based program where the insurer offers one |
| Vehicle make, model, and trim | High, at purchase time | Immediate at policy start | Repair cost, theft rate, and safety rating drive this more than sticker price alone |
| Liability limits and deductible | Full control | Immediate | Pure trade-off between premium cost and out-of-pocket exposure in a claim |
| Continuous coverage history | High, going forward | Immediate once re-established | A lapse in coverage tends to raise cost even after new coverage starts |
| Credit-based insurance score | Moderate, indirect | Slow | Not used in every state; where used, it reflects broader financial history, not driving behavior |
| Marital status / household composition | None as a rating strategy | Immediate if status changes | Statistical correlation with claims frequency, not a behavioral judgment |
| Prior claims (any household vehicle) | Low once filed | Slow to fade | Frequency matters more than the dollar size of a single claim in most models |
Reading the table this way reframes the whole “why doesn’t my rate match theirs” question. The factors with the least driver control — territory, age, household composition — are also often the ones with the biggest baseline impact, which is exactly why two people who each feel like careful, responsible drivers can still see very different numbers. The factors you can move — mileage, deductible, coverage limits, continuous history — are worth optimizing, but they’re adjustments around an edge, not a rewrite of the whole equation.
None of this means a quote you receive is fixed or fair by default; it means the difference between quotes is traceable, factor by factor, if you ask each insurer for the breakdown or run the same coverage profile through multiple quoting tools. Before assuming a rate is wrong, or that a neighbor is somehow getting a better deal for the same risk, check whether the comparison is actually apples to apples: same limits, same deductible, same vehicle trim, same reported mileage. Most of the “unexplained” gap closes once those inputs are matched — and what’s left over is usually territory and history, which is arithmetic you can understand even when you can’t change it.